Categoria: English

  • STJ: Late disclosure by arbitrator does not prevent annulment

    STJ: Late disclosure by arbitrator does not prevent annulment

    The duty of disclosure in commercial arbitration

    Arbitration has consolidated itself as the preferred method for resolving complex business disputes, including corporate conflicts and issues involving foreign direct investment in Brazil. The attractiveness of this model is based on the technical expertise of the adjudicators, confidentiality, and the speed of the procedure.

    However, the legitimacy of arbitration depends directly on the trust the parties place in the chosen arbitrators. This is where the duty of disclosure comes into play. This legal concept requires that anyone appointed to act as an arbitrator must proactively and immediately disclose any fact or circumstance that could raise justifiable doubts about their impartiality or independence.

    The understanding of the Superior Court of Justice

    The Superior Court of Justice (STJ – Brazil’s highest court for non-constitutional matters) has established an important understanding regarding the limits and consequences of breaching this duty. The court ruled that late disclosure by the arbitrator does not prevent the annulment of the arbitration.

    In practice, this indicates that the obligation of transparency does not allow for later corrections that harm the parties’ right to choose. If an arbitrator had a potential conflict of interest and did not declare it at the appropriate time, the fact that they revealed this information late does not validate the procedure. The initial omission is sufficient to support a request to annul the arbitral award before the Judiciary, as it compromises the foundation of trust in the system.

    Practical implications for companies and investors

    For executives, board members, and investors, the STJ decision delivers a clear message about the strictness of the Brazilian arbitration system. National case law acts to preserve the fundamental guarantees of the process and does not tolerate flexibility when it comes to guaranteeing an impartial judgment.

    When structuring commercial contracts or shareholder agreements, companies must be aware that conducting arbitration proceedings requires continuous diligence. Immediate and complete transparency protects the integrity of the procedure and prevents disputes resolved in arbitration from being subsequently annulled, which would generate additional costs, delays, and instability for businesses.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • Tax Reform and the Aviation Sector: Measures Under Study

    Tax Reform and the Aviation Sector: Measures Under Study

    The transition to the new consumption tax system in Brazil brings specific challenges for various sectors of the economy. In the case of commercial aviation, the National Treasury Attorney General’s Office (PGFN) and the Ministry of Ports and Airports have initiated joint studies to structure measures that mitigate the potential impacts of the tax reform on airline operations.

    The Impact of the New Tax System

    The tax reform consolidates several current taxes into a dual Value-Added Tax (VAT) model. Although the central goal is simplification and transparency, the change in the calculation base and reference rates may alter the cost dynamics of complex services, such as air transport. To avoid economic imbalances, the government is evaluating adjustments on three main fronts.

    1. Rate Reduction

    The first point under analysis by the authorities is the possibility of a rate reduction for the sector. In the VAT model, applying a single standard rate could represent an increase in the operating costs of airlines, which currently operate under regimes with specific characteristics. Evaluating a reduced rate seeks to maintain the viability of passenger and cargo transport, which is essential for the country’s infrastructure and logistics.

    2. Rules for Claiming Credits

    The core of the new tax system is full non-cumulativity, a mechanism by which the tax paid at one stage of the production chain generates a credit to be deducted at the next stage. The PGFN and the Ministry are studying how claiming credits will work in practice for aviation. Airlines have unique cost structures, involving aircraft leasing, the purchase of aviation kerosene (QAV), and maintenance expenses. Structuring clear rules so that these inputs generate tax credits efficiently is fundamental to avoid cascading taxation.

    3. Taxation of International Flights

    Cross-border operations are also a focus of the discussions. In international trade and the provision of global services, the common practice is to exempt exports to ensure competitiveness. Government studies seek to define how the new VAT will be applied or mitigated on international routes, considering the treaties to which Brazil is a signatory and the need to keep companies operating in the country competitive on the global stage.

    Perspectives for the Sector

    The joint initiative of the PGFN and the Ministry of Ports and Airports demonstrates an institutional effort to adapt the new constitutional rules to the complex operational reality of aviation. For investors, founders, and executives in the logistics and aviation sector, monitoring these definitions is a strategic step, as the complementary laws will dictate the tax dynamics for the coming decades.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • China’s New Arbitration Law and the Role of the Judiciary

    China’s New Arbitration Law and the Role of the Judiciary

    Resolving commercial disputes in the international arena requires predictability, especially in cross-border investment and trade relations. Recently, the Chinese legal system underwent a relevant update with the approval of amendments to its Arbitration Law. For foreign investors and companies operating in the country, understanding the transition to this new legal framework is a fundamental step.

    In this scenario, the judiciary’s role is essential to ensure legal certainty during the legislative change. China’s Supreme People’s Court (SPC) has begun preparing the transition guidelines necessary for applying the new rules.

    The Role of the Supreme People’s Court in the Transition

    The Supreme People’s Court is the highest court in the country and is responsible for issuing judicial interpretations. These documents function as binding guidelines for the application of the law by lower courts. With the new arbitration legislation, the SPC faces the challenge of aligning daily judicial practice with the recently approved changes.

    To achieve this, the court will conduct a comprehensive review of existing judicial interpretations and normative documents dealing with arbitral proceedings. The main objective of this review is to ensure that the content of the new Arbitration Law is effectively implemented and understood uniformly throughout the country.

    Review of Guidelines and Procedures

    The transition process requires a thorough analysis of current rules. The court will need to determine which documents and guidelines remain valid, which require amendments, and which must be revoked due to incompatibility with the new law.

    The involvement of state courts is frequently required to support arbitral proceedings. Without a clear transition guide, the efficiency of these procedures could be compromised. The drafting of these guidelines by the SPC aims precisely to avoid interpretive gaps and ensure that judicial support for arbitration continues to operate stably.

    Practical Considerations for Investors

    For international companies with interests in China, monitoring this normative transition is strategic. Clarity in arbitration rules reduces risks when drafting commercial contracts and guarantees greater legal certainty in the event of disputes.

    The consolidation of the new legal framework will require attention to detail from companies and their legal advisors. Following the future publications and interpretations of the Supreme People’s Court will allow investors to adapt their dispute resolution clauses to the updated regulatory environment.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • STF forms a majority on cargo insurance by carriers

    STF forms a majority on cargo insurance by carriers

    The STF (Brazil’s Supreme Federal Court) has formed a majority of votes to determine that the obligation to purchase cargo insurance falls on the carrier. The decision has a direct impact on the transport and logistics sector in Brazil, redefining insurance responsibilities in the movement of goods.

    The context of the STF decision

    The formation of a majority in the STF indicates that most of the Court’s justices have already voted in favor of the thesis that the transport company, and not necessarily the owner of the goods, holds the primary responsibility for purchasing the insurance policy against transport risks. Cargo insurance is the legal and financial instrument that protects the value of transported goods against loss, damage, or theft during transit.

    Although the majority is already formed, the trial may still undergo developments before its formal conclusion and the publication of the appellate decision (the final written ruling).

    The position of the CNI

    Given the progress of the trial in the Supreme Court, the CNI (National Confederation of Industry) intervened in the process. The entity representing the industrial sector requested that the trial be postponed for 180 days.

    The CNI’s central argument for the suspension request is the existence of ongoing legislative proposals in the National Congress that address the same topic. The confederation argues that the debate within the Legislative Branch should be awaited, thus preventing a final judicial decision from conflicting with a potential new law on cargo transport insurance.

    Perspectives for the sector

    The definition of who must purchase the insurance affects cost structuring, freight pricing, and risk management in logistics operations. Companies operating in the supply chain, whether shippers or carriers, should monitor the conclusion of the STF trial and the progress of the bills in Congress to adapt their commercial practices and transport contracts to the new legal guidelines.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • Risks in the Invalidation of Working Hours Compensation Agreements

    Risks in the Invalidation of Working Hours Compensation Agreements

    Working hours management is one of the areas requiring the most attention in corporate administration. Recently, discussions regarding the invalidation of working hours compensation agreements have gained prominence in the legal landscape, especially with the analysis of Theme 19 of Repetitive Appeals by the TST (Brazil’s Superior Labor Court). Understanding these rules is essential for executives and human resources managers seeking to mitigate labor liabilities.

    What is a working hours compensation agreement?

    A compensation agreement is a legal arrangement that allows an employee to work a few extra hours on certain days in order to take time off or work less on others. The most common example in the Brazilian corporate environment is adding daily minutes from Monday to Thursday to eliminate Saturday shifts. When this agreement is formalized and executed correctly, the company does not need to pay overtime for the additional hours worked on the compensation days.

    How does the invalidation of the agreement occur?

    The invalidation of this agreement happens when the agreed rules are not followed in daily practice. The main reason Labor Courts annul the validity of the compensation is the habitual performance of overtime. If the employee routinely exceeds the hour limit stipulated for compensation, courts understand that the agreement has lost its original purpose, which was precisely to avoid excessive working hours.

    Financial impacts and TST’s Theme 19

    When the agreement is judicially invalidated, there is a need to reassess how the hours worked should be remunerated. Theme 19 of Repetitive Appeals at the TST addresses exactly the practical and financial consequences of this invalidation on the calculation and payment of overtime.

    The central discussion in the courts involves defining the form of remuneration: whether the company must pay the full overtime rate, which includes the regular hour plus the overtime premium, or only the overtime premium for those hours that had already been compensated but exceeded the daily limit. The clear definition of these criteria through repetitive appeals ensures greater legal certainty, as it standardizes decisions in lower courts and helps companies accurately calculate potential labor liabilities.

    Best practices for corporate governance

    To avoid the invalidation of the compensation agreement and unforeseen overtime costs, companies should adopt strict time-tracking controls and actively monitor their teams’ work routines. It is essential to ensure that employees respect the daily working hour limits established in the agreement. The requirement of habitual overtime should be avoided, thereby preserving the validity of the compensation and the financial health of the organization.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • Update on NDRC Rules for Chinese Investments

    Update on NDRC Rules for Chinese Investments

    Recent publications from specialized Asian law outlets, such as China Law Insight, indicate that China’s National Development and Reform Commission (NDRC) is refining its rules applicable to Chinese outbound investments. For Brazilian executives, founders, and managers dealing with foreign capital, understanding the role of this agency is a fundamental step in structuring international business.

    What is the NDRC and what is its function?

    The NDRC is China’s main economic planning body. Among its various responsibilities, the agency regulates and supervises the flow of Chinese capital leaving the country for acquisitions, mergers, or the establishment of companies abroad—known as Foreign Direct Investment (FDI).

    In practice, when a Chinese company decides to invest in a Brazilian company, it generally needs to go through an approval or registration process with the NDRC, in addition to other local regulatory bodies. This procedure ensures that the investment aligns with the Chinese government’s macroeconomic and strategic guidelines.

    The impact of regulatory changes abroad

    Although the specific details of the recent regulatory refinements are still being mapped by the market, any alteration in the NDRC’s guidelines tends to generate practical effects in the countries receiving these investments. Historically, updates to these rules pursue two main objectives:

    • Process optimization: Simplifying registration for investments in sectors considered strategic or low-risk.
    • Greater control: Increasing rigor and compliance regarding capital outflow in sensitive industries.

    For the Brazilian market, which is one of the main destinations for Chinese capital in Latin America, these movements in Beijing can directly influence the timeline of corporate transactions. Sectors such as infrastructure, energy, technology, and agribusiness are frequently impacted by the agility or rigor of regulatory approvals at the capital’s origin.

    Practical considerations for Brazilian companies

    Structuring transactions involving foreign capital requires a global perspective. When a Brazilian company enters into negotiations with Chinese investors, it is prudent to consider the timing and requirements of foreign regulatory bodies at the initial phase of the project.

    Some recommended practices include:

    • Discussing openly with the investor the need for prior NDRC approval.
    • Including contractual clauses that provide realistic deadlines for closing the deal, considering the review time of international bodies.
    • Monitoring global regulatory trends to anticipate potential documentary requirements.

    The refinement of outbound investment rules by China demonstrates the dynamism of the global market. Monitoring these updates allows Brazilian companies to structure safer and more predictable transactions.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • De Facto Partners and the Right to Demand Accounting from Managers

    De Facto Partners and the Right to Demand Accounting from Managers

    The STJ (Brazil’s Superior Court of Justice) issued a relevant decision for corporate governance and corporate dispute resolution in Brazil. The court ruled that filing a lawsuit to demand accounting from a company manager does not require the plaintiff to be formally included in the articles of association. For the STJ, proving the legal relationship with the company is sufficient.

    To understand the impact of this understanding, it is important to clarify two fundamental concepts in the business environment. The action to demand accounting is a legal procedure in which a person requests that the party responsible for managing resources presents a detailed breakdown of revenues, expenses, and investments. The figure of the de facto partner refers to someone who has rights and acts in the company’s dynamics, but does not yet have their name officially registered in the corporate documents at the Board of Trade (Brazil’s commercial registry).

    The Nature of Corporate Registration

    In Brazilian corporate law, the main function of public registration is to provide publicity to the company’s acts and produce effects against third parties. However, the relationship between the partners or investors themselves can exist through joint action and the pursuit of a common economic activity, regardless of immediate documentary regularization.

    The STJ decision consolidates the view that the absence of formality does not serve as a shield for managers to evade the duty of transparency. Managing third-party resources requires continuous and documented accounting. The court understands that the existence of a company or an investment relationship is not exclusively conditioned on its formal registration. This protects the right to information of those who already integrate the operation in practice.

    The Fiduciary Duty of Managers

    Managing a business company carries non-negotiable fiduciary duties. Loyalty and transparency are the most evident. When an executive or managing partner assumes the management of capital, they act on behalf of the corporate interest and the holders of that capital. The STJ’s understanding reinforces that this fiduciary duty is not activated only by registration at the Board of Trade, but by the reality of the business relationship.

    This is especially critical in foreign direct investment scenarios and cross-border operations. International investors frequently structure their operations in Brazil through investment vehicles or partnership agreements that may take time to be fully reflected in the formal corporate structure. Knowing that the Brazilian legal system allows demanding accounts based on the reality of the legal relationship provides greater predictability to foreign capital.

    Practical Impacts for Investors and Executives

    This understanding brings direct implications for founders, investors, and executives operating in the Brazilian market. In mergers and acquisitions (M&A), capital contributions, or corporate restructurings, a time gap commonly occurs between signing a commercial agreement and effectively changing public records.

    For managers, the rule reinforces the need to maintain rigorous financial controls and solid corporate governance from the beginning of any corporate arrangement. The duty to account exists even for those business partners who are still awaiting the formalization of their entry into the company.

    On the other hand, for investors and partners who are not yet in the articles of association, the decision reaffirms the protection of their property rights. To exercise this right, the investor must have adequate documentation. Preliminary contracts, memorandums of understanding, or investment agreements can prove the legal relationship with the operation.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.
  • Reciprocity Law: Brazil Evaluates Countermeasures Against the US

    Reciprocity Law: Brazil Evaluates Countermeasures Against the US

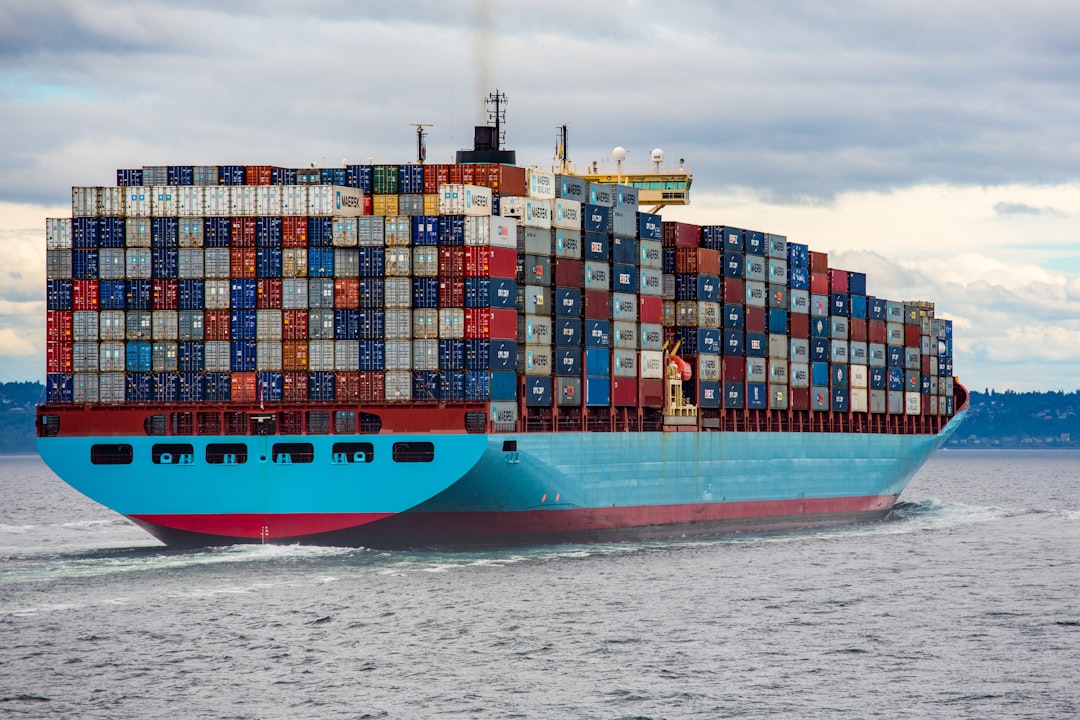
    The Ministry of Finance has formalized the opening of a process to evaluate the application of commercial reciprocity measures against the United States. The Brazilian government’s initiative emerges as a direct response to the recent imposition of a 37.5% surcharge on certain products exported by Brazil, a measure that directly affects approximately US$ 6.6 billion in national exports.

    The US government justified the tariff increase by alleging supposed unfair trade practices and the existence of forced labor in production chains. In response, in addition to triggering the World Trade Organization (WTO), Brazil initiated internal procedures to evaluate retaliations. However, Finance Minister Dario Durigan highlighted that the adoption of any countermeasure will be preceded by a broad dialogue with Brazilian business leaders and foreign investors, ensuring predictability for the market.

    The Legal Mechanism: Law No. 15,122

    The legal basis for the possible Brazilian response is Law No. 15,122, sanctioned last year unanimously in the National Congress, known as the Reciprocity Law. This normative instrument establishes objective criteria for Brazil to suspend commercial concessions whenever an international partner adopts unilateral actions, policies, or practices that harm national economic competitiveness.

    In legal and practical terms, if a country with which Brazil maintains commercial relations imposes unjustified barriers, the legislation allows the Brazilian State to adopt measures of the same nature to rebalance the trade scale. A fundamental principle of this law is proportionality: countermeasures must be applied, as far as possible, in the exact proportion of the economic damage caused to Brazil by the other country or economic bloc.

    The Impact on the Brazil-US Investment Axis

    The commercial relationship between Brazil and the United States is one of the structural pillars of foreign direct investment (FDI) in Latin America. Entire production chains, from agribusiness to the technology sector, depend on the continuous flow of capital, the import of US inputs, and the export of Brazilian manufactured products and commodities.

    The potential application of the Reciprocity Law has the potential to significantly alter the cost dynamics for companies with cross-border operations. Therefore, the government’s caution in not applying automatic sanctions is seen as a move to protect corporate governance and the stability of multinational operations installed in the country.

    What are the possible countermeasures?

    If the government decides to move forward with the application of Law No. 15,122 after concluding the hearing phase, the actions implemented to compensate for the US tariff increase must be restricted to the mechanisms provided in the legislation and indicated in the process. According to information from the original source, the tools under evaluation involve the suspension of commercial concessions and the possibility of imposing taxes on products imported from the infringing country. Such measures aim to rebalance market conditions, always respecting the principle of proportionality in relation to the damage suffered by Brazilian exports.

    The Relevance of Hearing the Productive Sector

    The decision to hear the private sector before applying sanctions is an essential step in modern regulatory law to mitigate unwanted risks. The Minister of Finance emphasized that a reciprocity process conducted with seriousness demands the active listening of potential stakeholders and affected parties. This approach prevents a commercial retaliation from ultimately burdening the Brazilian domestic market itself, making vital inputs for national industry more expensive or discouraging new foreign capital contributions.

    Practical Perspectives for the Market

    For companies operating in international trade, the current scenario requires continuous monitoring. The opening of the reciprocity process does not result in the immediate application of tariffs, but it signals a possible change in the bilateral customs structure in the medium term.

    It is recommended that executives, founders, and supply chain managers map their exposure to the tariffs and closely follow the Ministry of Finance’s consultation schedule. The active participation of affected companies in these dialogues is the appropriate means to demonstrate to the government the real impacts that countermeasures may cause on their production costs and global competitiveness.

    Regulatory predictability and private sector participation are determining factors for maintaining a secure and attractive business environment for foreign capital.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.

  • US warns of transshipment of Chinese products in the region

    US warns of transshipment of Chinese products in the region

    A recent report released by the White House placed nine Latin American countries, including Brazil, on a United States government watchlist. The document indicates that these nations present a high risk for illegal transshipment, a mechanism allegedly used by Chinese exporters to bypass US import tariffs. This measure reflects the intensification of global trade relations and brings direct implications for foreign trade operations in the region.

    The concept of illegal transshipment and rules of origin

    In customs law and international trade, illegal transshipment occurs when goods are sent to an intermediary country before reaching their final destination, with the goal of altering the declared origin of the products. This maneuver seeks to take advantage of lower import tariffs or avoid trade sanctions and surcharges applied to the actual country of origin of the goods.

    To combat this practice, customs authorities use the so-called rules of origin. This is a set of legal and technical criteria that determines the economic nationality of a good. For a product to change its origin, it must undergo a process of substantial transformation in the intermediary country. When a product is merely repackaged, simply assembled, or undergoes minimal modifications, it does not acquire a new origin for tariff purposes before US authorities.

    The scenario in Latin America

    Besides Brazil, the United States monitoring list includes Argentina, Chile, Peru, Costa Rica, the Dominican Republic, Mexico, Panama, and Colombia. The report highlights that more than forty countries worldwide present a high risk of being used as tariff evasion routes in the context of trade tensions between the United States and China.

    Practical impacts and the importance of compliance

    The inclusion of Brazil and other regional partners on this risk list signals a likely increase in the strictness of customs inspections by United States authorities. Companies that produce and export to the US market from Latin America may face additional documentary requirements and more frequent audits to prove the true origin of their products.

    Given this scenario of greater scrutiny, foreign investors and executives operating global supply chains must reinforce their internal compliance procedures. It is essential to maintain detailed and auditable documentation regarding the entire manufacturing process, the origin of acquired inputs, and the industrial transformations carried out within the national territory. Strict traceability of the production chain is the main tool to demonstrate the regularity of commercial operations, ensure the legal security of investments, and avoid the retention of goods in foreign markets.

    This content is for informational purposes only and does not constitute legal advice. For guidance on specific matters, consult a qualified lawyer.